


Good Morning Team.
When I first covered European Green Transition back in April, the stock was more of a pitch than a track record.
And as we all know, small cap growth stocks have a habit of going quiet between updates and then either disappointing or properly delivering (there is no in-between).
Several RNS releases later, EGT has firmly landed in the second camp.
Quick recap for anyone joining mid-story - EGT bought a profitable wind turbine servicing business — Earthmill, WEP, Silverford and Anemos — out of the liquidation of an Irish investment fund, for a fraction of what comparable businesses have changed hands for.
The pitch was a faintly boring, recurring-revenue O&M platform sitting in front of an enormous, newly-unlocked repowering opportunity, run by a management team with a track record of building things and selling them.
Four months on from completion, the numbers are doing what they were supposed to do.
Some of them are doing rather more than that.
The Repowering Engine Is Running Hot
This was always the number that mattered most, because it’s what drives a re-rating.
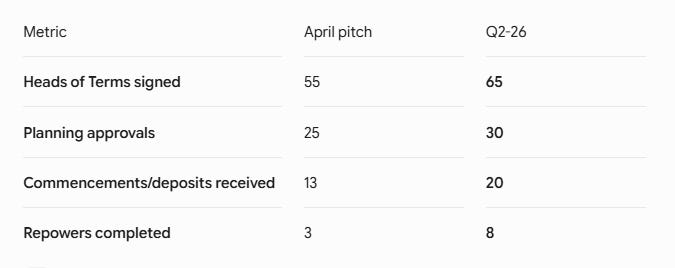
Look at that last row. Three repowers completed as of the April pitch, eight by the end of June — meaning five were completed in Q2 alone, more than the entire first three months of the year combined.
That’s a business that’s found its stride.
Run that quarterly pace forward and you land somewhere around 18-22 repowers for the full year — which puts Dave Broadbank’s original ‘over 20 repowers’ target, the boldest claim on the April investor call, squarely within reach.
Broadbank has been in this industry for 15 years and doesn’t strike anyone as a man prone to hype; when he said the pipeline for 2026 was essentially already full, the numbers since have backed him up.
And crucially, the addressable opportunity hasn’t shrunk as they’ve worked through it — EGT is still quoting the same circa 280 qualified prospects and the same £126 million theoretical pipeline value across its 900-turbine client base.
They’re converting the easy wins without visibly depleting the well.
Revenue Guidance Just Got Upgraded - Twice
The original pitch talked about growing from roughly £15 million toward a £50 million medium-term target. Four months in, here’s where things actually stand:
H1 2026 - £8.5 million in Wind Energy Services revenue (six months to 30 June)
Full-year 2026 guidance - £17-18 million, upgraded from the £14.7 million FY25 base
Statutory revenue to EGT itself - £6.8 million in just the four months since completion on 25 February
That £17-18 million full-year guidance was issued in the H1 trading update, after four months of live trading inside the group, and it’s higher than the organic growth trajectory implied back in April.
Management raising guidance this early, rather than hoping to hit an original number, is a critical signal.
The bulk of the £50 million target still sits ahead — plenty of the repowering orderbook hasn’t converted to billed revenue yet — but that’s the nature of a project pipeline with £100,000-150,000 staged deposits ahead of installation.
Money in the door now, revenue recognised as projects complete.
Given how the completion rate is accelerating, the read-through for H2 and into 2027 looks solid.
Anemos: Bigger Stake, Bigger Footprint
EGT also upped it 52% stake in Anemos to 79% in May, on the back of what it openly called strong early commercial traction.
Doubling down on the part of the portfolio it thinks has the longest runway.
The growth numbers back the conviction up:
90 turbines deployed (April)
119 turbines (May)
133 turbines (July)
That’s steady, monotonic growth every update, with contracts structured on five-year terms — meaning each new turbine added is locked-in recurring revenue for half a decade.
There was a small wrinkle disclosed in May — about £40,000 of overdue creditor obligations left over from the chaotic liquidation period Anemos was born into — but EGT resolved it immediately with a modest working-capital facility, and it’s also worth remembering this is a business that started trading in April 2025 that was orphaned by its parent’s insolvency five months later.
That it’s now on 133 turbines and drawing more capital commitment from its new owner, rather than being wound down, says more about its trajectory than one small overdue invoice does.
Management is also actively pursuing Anemos into adjacent markets — hydro, shipping, larger wind assets — exactly as flagged in April.
Nothing concrete to report there yet, but the stated ambition hasn’t wavered.
Balance Sheet: Boring, in the Best Way
The group remains completely debt-free, with £5.8 million cash at 30 June. No further dilutive fundraises, no surprises, no departure from the disciplined approach Friel laid out from day one.
In the spirit of balance: the Step 3 bolt-on M&A strategy — the part explicitly modelled on Renew Holdings’ roll-up — hasn’t kicked off yet, and there’s been no fresh news on monetising the non-core Olserum rare earths or Pajala copper assets since April.
Neither is remotely alarming four months post-completion; both are simply the next things to watch for, and both represent optionality that isn’t currently priced in regardless.
The Bottom Line
Four months ago this was a pitch resting on management’s word and a liquidation-discount purchase price. Today it’s a business that has hit its operational targets, upgraded its own revenue guidance, accelerated its repowering completions faster than even the bullish original target implied, and increased its conviction in the one genuinely optionality-rich asset in the portfolio.
None of that guarantees the share price does what Friel wants it to do this year.
But as far as ‘is the underlying business doing what they said it would?’
then the answer four months in is: yes, and in places, better than expected.
Which, for a growth story just out the gate, is exactly what I want to see.
Great update. It’s done really well and I do like the management!! Here’s looking forward to the future. Have a great weekend
Steady progress is the best kind and they are delivring,looking to invrease holdings here.